
For Ugandan businesses struggling to secure affordable capital, the search for financing is increasingly moving beyond commercial banks and traditional investors.
One emerging possibility is the use of fintech, blockchain and digital assets to connect businesses with new pools of capital, although questions around regulation, investor protection and the viability of the underlying businesses remain.
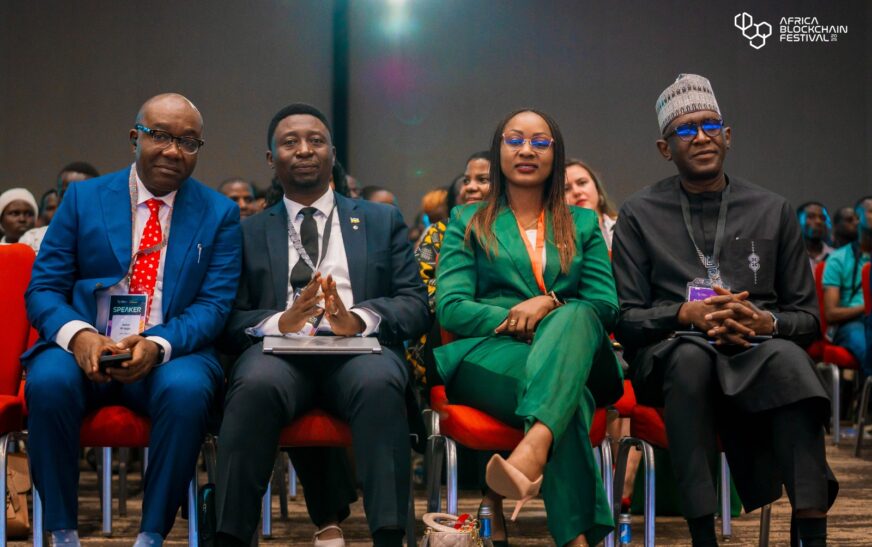
The debate is expected to feature prominently at the Africa Blockchain Festival 2026 in Nairobi, where investors, technology companies, policymakers and financial sector players from across Africa will meet from October 15 to 17.
The festival, to be held at the Sarit Expo Centre under the theme, “Capital, Code, and Continuity: Building Africa’s Permanent Digital Economy,” is expected to attract more than 3,000 delegates from more than 20 countries.
For Uganda, however, the significance goes beyond blockchain technology itself. The bigger question is whether emerging digital financial infrastructure can help businesses access capital that remains difficult to reach through conventional channels.
Beyond the bank
Ugandan businesses have traditionally relied on commercial banks, savings and credit institutions, development finance and private investors to raise capital.
But access to finance remains a challenge, particularly for small and growing businesses that may lack sufficient collateral, long credit histories or the scale demanded by conventional investors.
Fintech companies are exploring ways of changing parts of that equation.
Ugandan-founded tisini, for example, is developing technology that combines artificial intelligence and credit intelligence with blockchain infrastructure.
In November 2025, the company entered into a strategic partnership with Sphere Labs to integrate its credit intelligence with SphereNet, a blockchain network developed for financial applications.
According to Sphere Labs, the partnership is intended to support intelligent credit systems and create tokenised investment pathways linked to African credit assets.
In simple terms, tokenisation involves representing a financial or real-world asset digitally on a blockchain.
The attraction is that an asset can potentially be tracked and transferred digitally, which could reduce some of the transaction barriers associated with conventional investment structures.
For African businesses, this raises a broader question: can technology connect businesses seeking capital with investors looking for new opportunities?
A new role for fintech
Other Ugandan fintech companies are focusing on another part of the financial system: moving money.
Kampala-linked MUDA describes itself as liquidity infrastructure for the digital economy.
The company provides collections and payouts, virtual accounts, stablecoin wallets and services that allow digital assets to be converted into local bank or mobile money currencies.
MUDA says its platform supports USDC, USDT and cNGN stablecoins and operates across more than 50 corridors.
Its role is not primarily to raise capital for businesses. Rather, its infrastructure illustrates how fintech can facilitate movement of money between markets, an important requirement for businesses and investors operating across borders.
Equator Finance, trading as EQPay Finance Ltd, is similarly focused on financial infrastructure.
The Kampala-based company provides digital asset settlement, stablecoin liquidity, over-the-counter trading, remittances and cross-border payment services.
Equator Finance says it operates from Uganda and serves markets including Kenya, Nigeria and South Africa, with settlement corridors involving the Gulf, China and Japan.
Together, such businesses point to a financial system in which capital could move across borders more efficiently, while businesses and investors gain access to digital tools for transactions and settlement.
The investment question
The more ambitious proposition is whether blockchain can widen the pool of investors available to African businesses.
Africa has significant pools of capital, including pension funds, institutional investors, private equity, diaspora savings and individual investors. Yet connecting that money to businesses and productive assets can be difficult. Tokenisation is being explored as one possible bridge.
A business or financial asset represented digitally could, depending on the applicable legal and regulatory framework, be divided into units that investors can acquire and transfer.
But tokenisation does not eliminate investment risk, nor does technology automatically make an asset investable.
The underlying business, the quality of the asset, investor protections and the regulatory environment remain critical.
Supporters of tokenisation nevertheless argue that digital infrastructure could reduce some transaction costs and make certain investment opportunities easier to access.
For Uganda, where businesses continue to face challenges in accessing affordable finance, the potential is worth examining.
Regulation will matter
The expansion of blockchain-based finance also presents challenges for regulators.
Digital assets can move across borders quickly, while financial regulation remains largely organised around national jurisdictions.
Issues such as consumer protection, taxation, anti-money laundering requirements, licensing, digital asset custody and investor protection therefore become increasingly important as fintech companies develop new products.
These questions are expected to form part of the conversation in Nairobi.
The Africa Blockchain Festival programme includes sessions on capital, blockchain infrastructure, stablecoins, real-world assets and Web3 regulation, alongside investor forums and startup showcases.
Among the speakers listed for the 2026 edition is Isaac Wabuge, Country Manager for Kenya and Uganda at Yellow Card.
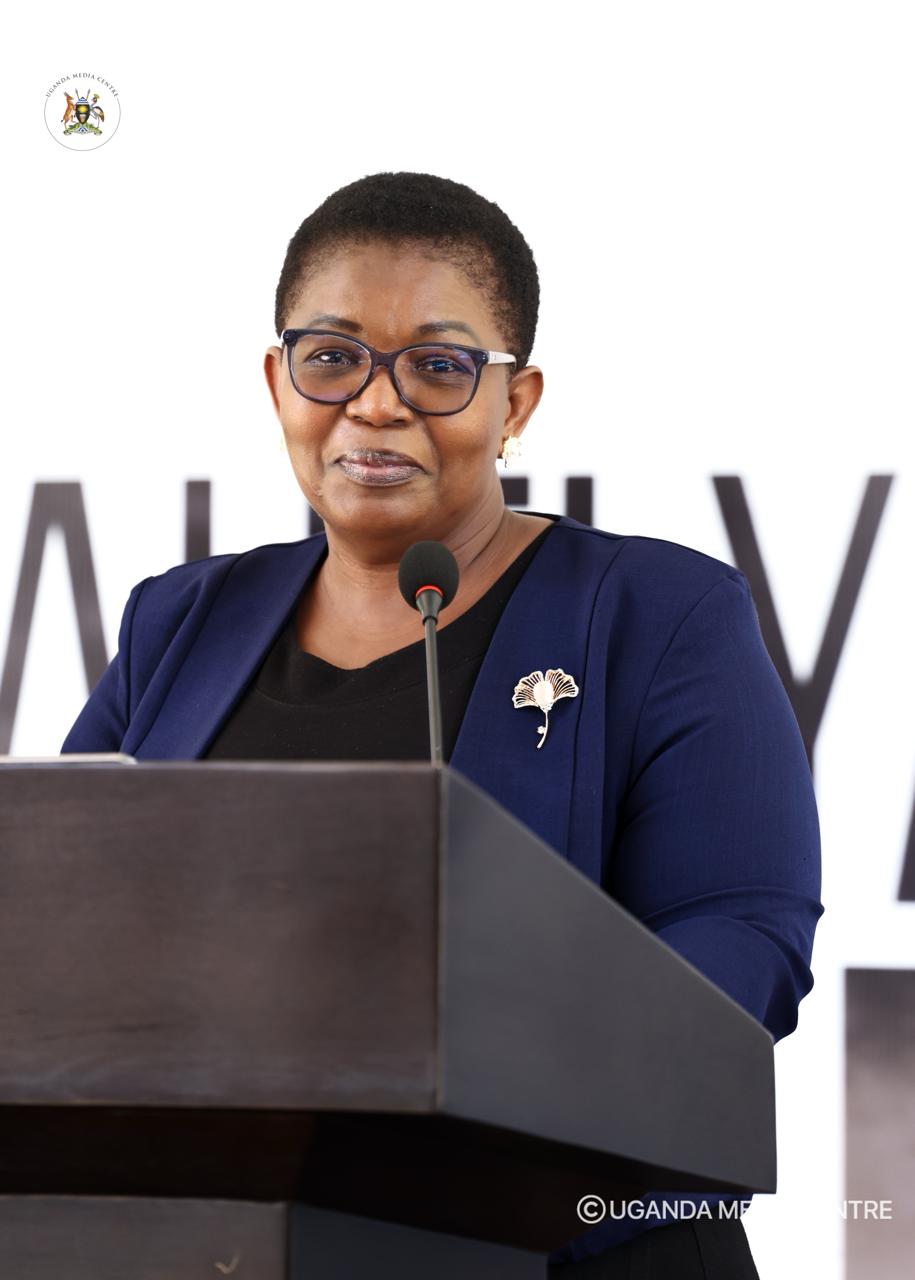
Uganda will also have government representation, with Minister for Science, Technology and Innovation Monica Musenero Masanza listed among the speakers at the opening ceremony.
An opportunity, not a shortcut
For Ugandan businesses, blockchain should not be viewed as a replacement for banks or other established sources of finance.
Its potential may instead lie in adding another layer to the financial system, improving how credit information is assessed, how assets are represented, how investors participate and how money moves between markets. That distinction matters.
Technology cannot by itself solve the problems of businesses that are not commercially viable or investors who lack confidence in an asset.
But if regulatory frameworks develop alongside the technology, fintech and blockchain could create additional channels through which capital is mobilised.
For Ugandan startups such as tisini, MUDA and Equator Finance, the Nairobi festival provides an opportunity to examine where this financial system is heading.
The bigger question for Uganda is whether local businesses and regulators can turn these emerging technologies into practical financial tools and whether they can help unlock pools of capital that traditional channels have struggled to reach.