
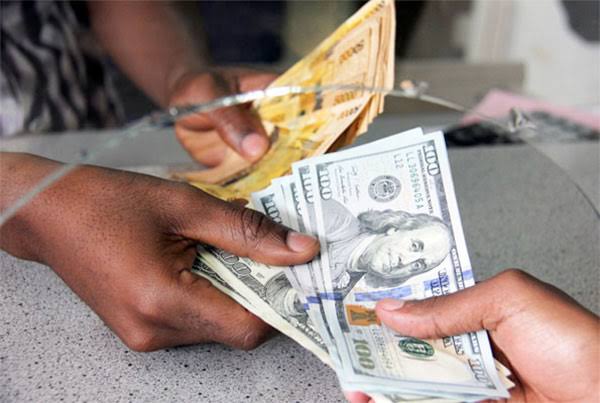
Banks and other financial institutions across the country will be required to integrate the National Security Information System (NSIS) into their operations to enable real-time verification of customers’ personal information against the National Identification and Registration Authority (NIRA) database.
The Minister for Internal Affairs, Ephraim Kamuntu, told Parliament that the new verification arrangement requires financial institutions to retrieve customers’ information directly from NIRA using their National Identification Numbers (NINs), instead of relying solely on information obtained from reading national identity cards.
Kamuntu said the system is intended to strengthen security, protect personal information and prevent the misuse of identity details in financial transactions.
“The new system was intended to improve security, privacy and data protection rights of personal data for any individual with a NIN. This was a significant departure from verification that depended only on information presented on reading the ID document,” Kamuntu said.
He was responding to concerns raised by Paul Mwiru (NUP, Jinja South Division East) during Wednesday’s plenary sitting, November 18, 2026, over the new identity verification requirements for financial transactions.
Mwiru questioned why financial institutions could not continue using information previously collected from customers when they registered using their old national identity cards, arguing that the new process had created unnecessary difficulties for the public.
“You have added an extra burden to Ugandans and creates extra charges. If you go to NIRA, it is not easy to get the required confirmation letters,” Mwiru said.
Kamuntu acknowledged that the transition had required banks and telecommunications companies to make significant technological upgrades, but said the integration process had progressed more slowly than anticipated.
He told MPs that NIRA had shared integration guidelines with 107 partner institutions, but only 10 had started transacting through the new system by October 28, 2026.
“NIRA shared integration guidance with 107 partners and as at 28 October 2026, 10 partners were transacting on the new system. Uganda Bankers’ Association reported that many member institutions were still installing compatible biometric readers,” Kamuntu said.
The minister advised that customers whose identity cards cannot be verified at the point of service can have their information confirmed through NIRA’s secure channel or obtain a Confirmation of Information Letter for the particular transaction.
However, the arrangement triggered concerns among MPs over who would bear the cost of obtaining the confirmation letters, particularly where customers are required to produce them because financial institutions have not completed their technological upgrades.
Denes Sekabira (NUP, Katikamu County North) questioned why customers should pay for documentation needed to facilitate transactions initiated through financial institutions.
“Each time you go to a bank and are required to have your data transmitted, a charge will be imposed, yet they should have the system in place. Some charges may be borne on a client in trying to stabilise a microfinance institution that is trying to equip itself,” Sekabira said.
Deputy Speaker Thomas Tayebwa, however, defended the new verification arrangement, saying it would strengthen Uganda’s efforts to combat money laundering and terrorist financing.
He said the country had previously faced the risk of being blacklisted by the Financial Action Task Force (FATF) because of weaknesses that allowed people to use forged national identity cards to facilitate illicit financial transactions.
“We passed laws to remove Uganda from the grey list of the Financial Action Task Force regarding money laundering. Uganda was about to be blacklisted because people used forged national IDs to launder money and finance terrorism. The new move will support the country’s efforts in ensuring that we do not take a step back,” Tayebwa said.
The new verification arrangement is part of efforts to strengthen the integrity of identity information used by financial institutions, although questions remain over the pace of integration and the additional costs customers may incur during the transition.